The short answer
Some insurers ask about or require physical security such as grilles, especially for shops holding cash or high-value stock. Whether a grille affects your cover or premium is the insurer's decision, so get any requirement in writing before choosing a product.
When do insurers specify grilles?
Commercial policies for shops, pharmacies, jewellers and stockrooms sometimes include security conditions, such as grilles or shutters on specified openings or a certified rating. Home policies are more likely to focus on door and window locks.
What should I ask my insurer?
- Which openings need protection
- Whether a specific type or certified rating is required
- Whether the grille must be locked at specific times
- What evidence they need after fitting
What can we provide?
A written quote listing products, a schedule of grilles, and for certified products the manufacturer's certificate reference.
Will a grille lower my premium?
We cannot promise that. Some insurers take security into account and some do not.
Sources
This guide is general information, not legal advice. Rules differ between England, Wales, Scotland and Northern Ireland; check with your council, building control or insurer where it matters.
Add Security Grilles UK as a preferred source on Google
Related grilles
Third-party certified grilles tested to LPS 1175 for high-risk premises and insurer requirements.
from £1,495 + VATLearn moreOpen-lattice grilles behind the shop window so the shop stays visible after closing but cannot be entered.
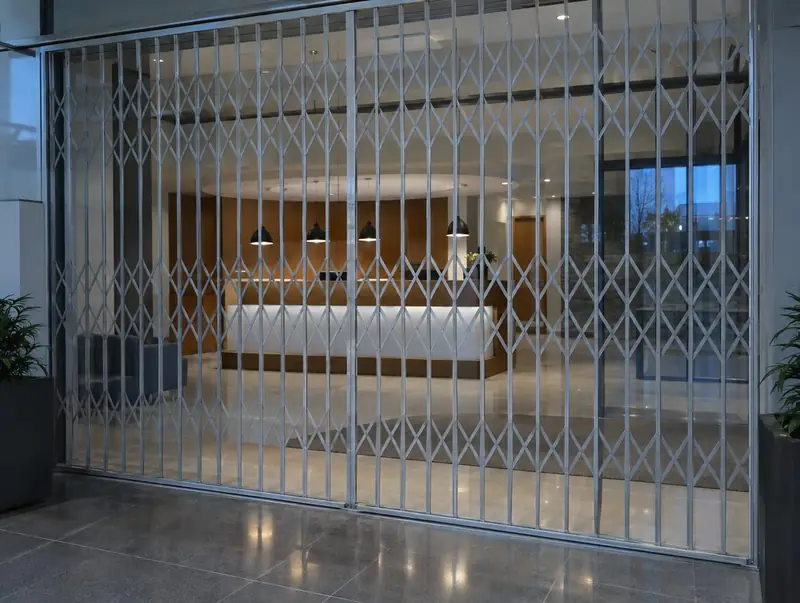
from £1,195 + VATLearn moreGrilles for offices, receptions, showrooms and business premises, sized for wide openings and daily use.
from £595 + VATLearn moreGrilles and grille doors inside buildings, for cash offices, stockrooms, server rooms and corridors.
from £595 + VATLearn more